Accessibility Options




 My Account
 Pre Approved Offer
 Make Payment
 Branch
Locator
 Xpress Services
-

Rs. 21,000* Cashback on availing Two Wheeler Loan.
-

Har Roz Gold Jeeto One Lucky Customer Wins a Gold Coin Every Day
-
Celebrate Festivities: Gold Loan + Movie Magic Win Ramayana Tickets with Every Gold Loan
-

Big Savings on Your LAP Loan Application HDB Loan Against Property with an application fee of just Rs. 2,999*
-

Khushiyon ka Season This Navratri, Bring Home Your Favourites with HDB Consumer Durable Loan
-

Khushiyon ka seasonThis Navratri Accelerate Your Business Growth with HDB Commercial Vehicle Loan
-
Khushiyon ka Season This Navratri Harvest Prosperity with HDB Tractor Loan
-
Get an Instant Salaried Personal Loan Now! With Attractive Interest Rates*
-

Pre-Owned Car Now Yours! Fulfill Your Dream Drive with HDBFS Car Loan
-
Hyundai - Let's Make It Big Now Own Your Favorite Car with HDBFS
-
Get Honda Two-Wheeler at Low DP Applicable for Honda Shine 100 & Activa only
-
Celebrate Sangeetha's 52nd Anniversary Sale Win a Gold Coin & Get Assured Vouchers worth Rs.60,000*
-
Instant Personal Loan Get an Instant Personal Loan now for upto Rs. 25 Lakhs!
-

Instant Pre-approved Offers Apply for Pre-approved loans in just 5 mins with Zero documentation!
-
HDB ontheGo App One application to view & manage your loan account & also apply for new loan
-
Rs. 21,000* Cashback on availing Two Wheeler Loan.
-
Har Roz Gold Jeeto One Lucky Customer Wins a Gold Coin Every Day
-
Celebrate Festivities: Gold Loan + Movie Magic Win Ramayana Tickets with Every Gold Loan
-
Big Savings on Your LAP Loan Application HDB Loan Against Property with an application fee of just Rs. 2,999*
-
Khushiyon ka seasonThis Navratri Accelerate Your Business Growth with HDB Commercial Vehicle Loan
-
Khushiyon ka Season This Navratri Harvest Prosperity with HDB Tractor Loan
-
Get an Instant Salaried Personal Loan Now! With Attractive Interest Rates*
-
Get an Instant Salaried Personal Loan Now! With Attractive Interest Rates*
-
Pre-Owned Car Now Yours! Fulfill Your Dream Drive with HDBFS Car Loan
-
Hyundai - Let's Make It Big Now Own Your Favorite Car with HDBFS
-
Get Honda Two-Wheeler at Low DP Applicable for Honda Shine 100 & Activa only
-
Celebrate Sangeetha's 52nd Anniversary Sale Win a Gold Coin & Get Assured Vouchers worth Rs.60,000*
-

Cashback offers on Iphone17 Pro Cashback offers upto Rs. 5,100*
-
Instant Personal Loan Get an Instant Personal Loan now for upto Rs. 25 Lakhs!
-
Instant Pre-approved Offers Apply for Pre-approved loans in just 5 mins with Zero documentation!
-
HDB ontheGo App One application to view & manage your loan account & also apply for new loan
- Home
-
About Us
-
Products
- Hot Offers NEW
- Blogs
-
Investors
-
Customer Services
- Careers
-
CSR
 My Account
 Pre Approved Offer


Call Us
+91 44 42984541(Charges Applied)10.00am-6.00pm, Mon-Fri (Excluding Holidays)
Follow Us
Buying a New Bike This Diwali? Complete Two-Wheeler Loan Checklist
2026-10-08


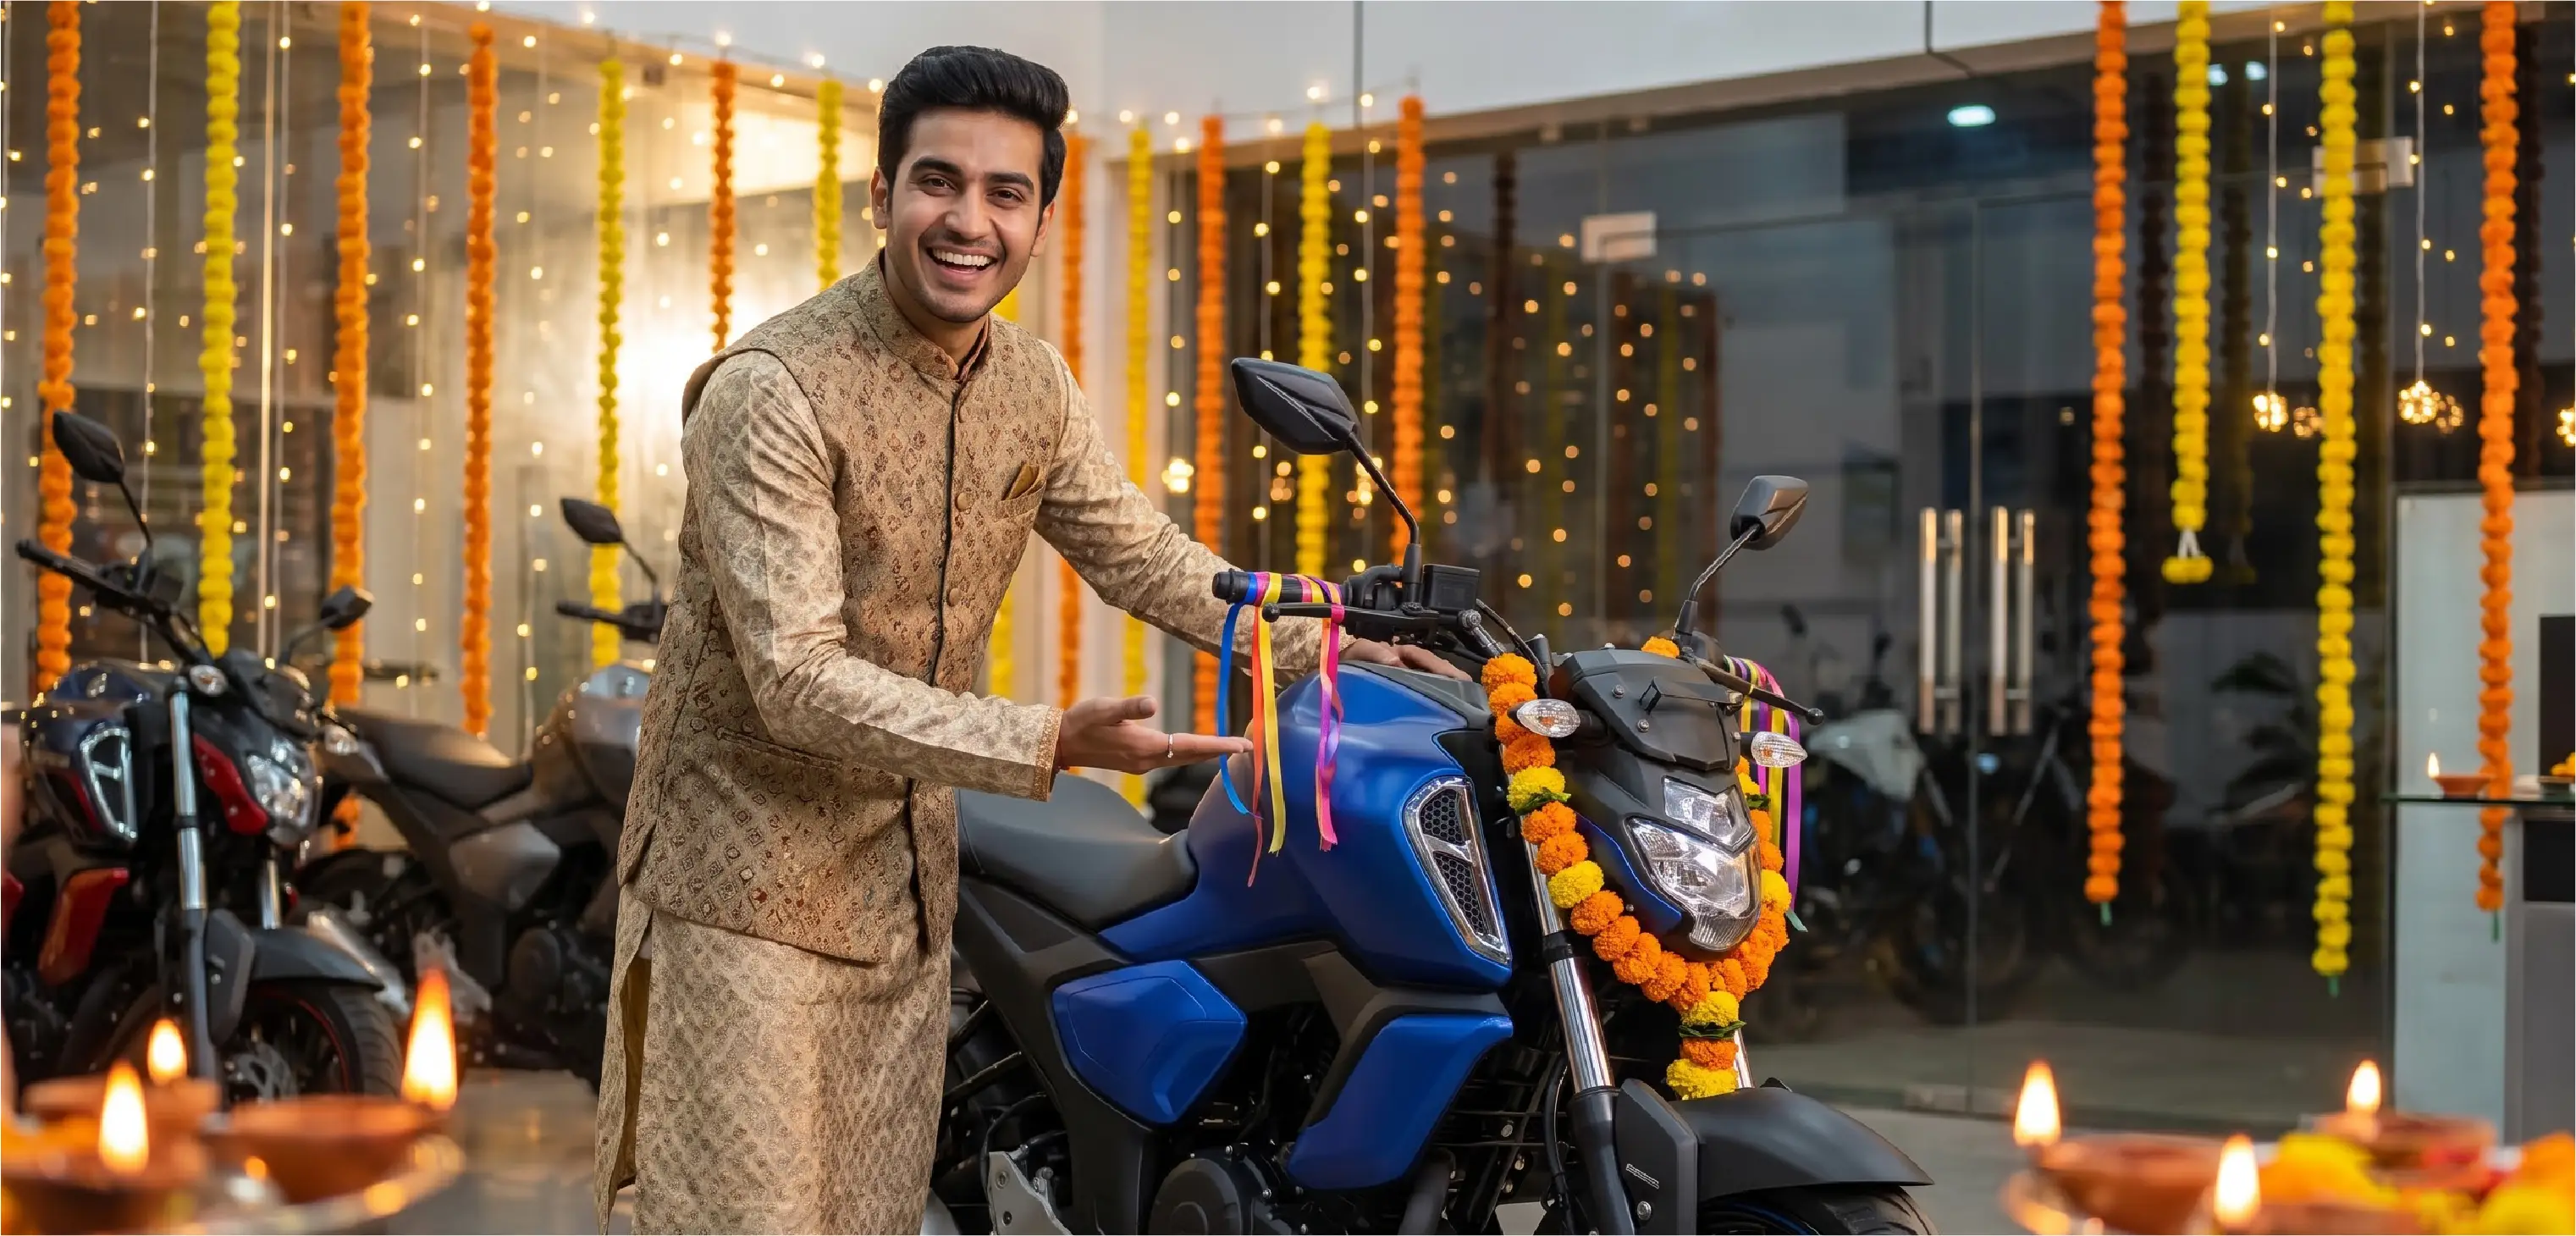
Diwali is often associated with new beginnings, and buying a new bike can be an exciting way to celebrate the event. Whether one requires a bike for personal or professional purposes, loans will help make the process of purchasing smoother. But festive discounts may distract buyers from the loan terms and make them focus only on the vehicle.
A two-wheeler loan checklist can help you evaluate your budget, documents, eligibility, EMI, tenure, and other terms before signing the agreement. Here are the key points to check.
1. Set Your Two-Wheeler Budget
Start by deciding how much you can comfortably spend on the bike. Do not consider only the showroom price. The on-road cost can include registration, insurance, taxes, and other applicable charges.
Also account for fuel, servicing, maintenance, insurance, parking, and accessories. Then decide how much you can pay as a down payment and how much you need to finance.
A clear budget helps prevent affordability problems after the EMI begins.
2. Check Your Loan Eligibility
Prior to applying, be sure that you are eligible for the loan from the lender. Eligibility may vary based on aspects such as age, residence, employment status, income, existing financial commitments, and creditworthiness.
For instance, HDB Financial Services notes that People who are interested in applying for the company’s two-wheeler loans should be Indian residents and above the age of 21 years. The company lends to both salaried people and self-employed people depending on their needs.
The eligibility check will help you get all the required information.
3. Check Your Credit Profile
Your credit score can affect the way you are assessed by lenders regarding your loan application. It is always advisable to examine your credit report before applying for a bike loan.
Good credit behavior is an indication that the borrower repays on time. Try to sort out any arrears you may have before applying for a loan.
Income, existing liabilities, documentation, and other internal criteria can also matter.
4. Decide the Right Down Payment
A down payment is the amount you pay upfront towards the purchase, while the remaining eligible amount may be financed through a two-wheeler loan.
A higher down payment can reduce the amount you need to borrow and may consequently reduce the EMI. However, using all your available savings for the purchase may leave you with little money for emergencies.
Ensure that your contribution and savings balance each other out. HDB Financial Services claims that the two-wheeler loan it provides can cover 95 percent of the on-road price, depending on your eligibility.
5. Compare the EMI Before Choosing the Tenure
The EMI needs to be comfortable within the scope of your monthly income. The loan amount, interest rate, and loan term are all factors that contribute to the EMI.
A shorter tenure results in a higher EMI every month, while a longer tenure results in a lower EMI every month. However, a shorter tenure might save on interest, while a longer tenure results in higher interest.
Use a two-wheeler loan EMI calculator to calculate various options before taking a call. HDB Financial Services provides repayment terms ranging from 6 months to 48 months for eligible salaried and self-employed individuals.
Tenure should not be selected depending only on EMI because it depends upon stability of income, expenditure, present EMI, and savings.
6. Understand the Interest Rate and Loan Charges
Before agreeing, you should know about the interest rates and how the repayment amount is calculated. Don’t judge loans based on the EMI alone.
Review processing fees, documentation charges, applicable taxes, late payment charges, and any other costs mentioned in the lender’s terms.
Also check the lender’s current schedule of interest rates and charges because applicable fees can vary according to the product, applicant profile, and prevailing policy.
Understanding the complete cost helps you make an informed decision.
7. Keep Your Documents Ready
Documentation forms an integral component of the loan application process. Having your documentation in order can help facilitate the process.
Depending on the lender’s requirements and your profile, you may need identity and address proof, income documents, bank statements, photographs, and details of the bike being purchased.
HDB Financial Services lists documents such as Aadhaar, PAN, passport, voter ID, driving licence, and utility bills among possible identity or address documents.
Salaried applicants may need salary slips, bank statements reflecting salary credits, Form 16, or ITR, while self-employed applicants may need ITR and other applicable financial documents.
Document requirements are subject to the lender’s policy, so verify the current list before applying.
8. Verify the Bike’s On-Road Price
Examples of items that may be included in festive sales are discounts, exchange offers, accessories, and dealer sales. Obtain a detailed quote with all the on-road costs included.
Compare the quotation with the amount being financed. Make sure you understand which items are included and which are optional.
If accessories or add-ons are included in the financed amount, check their cost. Avoid increasing the loan simply because an item is offered during a promotion.
9. Read the Loan Agreement Carefully
Before taking up the loan, ensure that you have thoroughly gone through the agreement and other documents. This is very important as there are certain things like sanctioned amount, interest rate, tenure, EMI amount, etc., which you should know.
If anything is unclear, ask the lender for an explanation before signing.
HDB Financial Services states that foreclosure and part-prepayment charges may apply to its two-wheeler loans. Therefore, borrowers considering early repayment should check the applicable charges and current terms before making a decision.
10. Plan for EMI Payments
Plan for every EMI from the beginning.
Note the repayment date and maintain sufficient funds in the linked account. Setting up an available automated repayment facility can help reduce the risk of accidentally missing a payment.
A missed EMI can result in applicable charges and may affect your credit history. A small financial buffer can help manage unexpected expenses.
11. Consider Insurance and Other Ownership Costs
However, while you are planning for the loan, remember the costs involved even after the purchase. There are insurance costs, fuel, maintenance, servicing, tyres, repair costs, parking, and so forth.
If you calculate only the EMI, you may underestimate the actual monthly cost of owning the bike.
Estimate the EMI plus running and maintenance expenses to understand the real monthly cost.
12. Apply Through a Reliable Process
Once you have checked your budget, eligibility, documents, EMI, charges, and agreement terms, you can proceed with the application.
HDB Financial Services provides multiple ways to apply for a two-wheeler loan, including its online application process, HDB OnTheGo app, branch assistance, and phone support.
Its website states that the application involves entering basic details, verifying the mobile number, providing required information, and submitting applicable KYC and income documents.
Go through the official communication routes of the lending institution.
Your Diwali Two-Wheeler Loan Checklist
Before bringing your bike home this Diwali, check:
- On-road total cost
- Down payment
- Eligibility for loan
- Credit score
- Interest rate
- EMI payment
- Tenure of repayment
- Processing and other charges
- Documents required
- Pre-payment or foreclosure details
- EMI repayment date
- Insurance and running costs
- Loan agreement details
The festive expense has to be within the budget. Spending enough time on researching the loan beforehand will help you avoid any surprises in the future.
Final Thoughts
Buying a new bike during Diwali can be an exciting milestone, but the financing decision deserves as much attention as the vehicle itself.
A complete two-wheeler loan checklist helps you look beyond the festive price tag and consider affordability, eligibility, documentation, interest, EMI, tenure, charges, and long-term ownership costs.
In this way, you will be able to purchase while having a clearer understanding of your finances. Do an EMI calculation, prepare your documents, carefully go through the agreement, and select the mode of repayment according to your income.
With proper planning, your bike purchase for Diwali will not only be a celebration but also a beginning in life without any burden on your pocket.