Accessibility Options




 My Account
 Pre Approved Offer
 Make Payment
 Branch
Locator
 Xpress Services
-

Khushiyon ka seasonDrive Growth with HDB Commercial Vehicle Loan
-
Khushiyon ka Season Drive Growth with HDB Tractor Loan
-
Get an Instant Salaried Personal Loan Now! With Attractive Interest Rates*
-

Pre-Owned Car Now Yours! Fulfill Your Dream Drive with HDBFS Car Loan
-
Hyundai - Let's Make It Big Now Own Your Favorite Car with HDBFS
-

Get Honda Two-Wheeler at Low DP Applicable for Honda Shine 100 & Activa only
-
Celebrate Sangeetha's 52nd Anniversary Sale Win a Gold Coin & Get Assured Vouchers worth Rs.60,000*
-
Instant Personal Loan Get an Instant Personal Loan now for upto Rs. 25 Lakhs!
-

Instant Pre-approved Offers Apply for Pre-approved loans in just 5 mins with Zero documentation!
-
HDB ontheGo App One application to view & manage your loan account & also apply for new loan
-
Khushiyon ka seasonCelebrate the Devine Festive of Janmashtami and Grow Your Business with Commercial Vehicle Loan
-
Celebrate the Divine Festive of Janmashtami and Grow Your Business with Tractor Loan
-
Get an Instant Salaried Personal Loan Now! With Attractive Interest Rates*
-
Pre-Owned Car Now Yours! Fulfill Your Dream Drive with HDBFS Car Loan
-
Hyundai - Let's Make It Big Now Own Your Favorite Car with HDBFS
-
Get Honda Two-Wheeler at Low DP Applicable for Honda Shine 100 & Activa only
-
Celebrate Sangeetha's 52nd Anniversary Sale Win a Gold Coin & Get Assured Vouchers worth Rs.60,000*
-

Cashback offers on Iphone17 Pro Cashback offers upto Rs. 5,100*
-
Instant Personal Loan Get an Instant Personal Loan now for upto Rs. 25 Lakhs!
-
Instant Pre-approved Offers Apply for Pre-approved loans in just 5 mins with Zero documentation!
-
HDB ontheGo App One application to view & manage your loan account & also apply for new loan
- Home
-
About Us
-
Products
- Hot Offers NEW
- Blogs
-
Investors
-
Customer Services
- Careers
-
CSR


 My Account
 Pre Approved Offer


Call Us
+91 44 42984541(Charges Applied)10.00am-6.00pm, Mon-Fri (Excluding Holidays)
Follow Us
Mortgage Loans for Self-Employed vs Salaried Borrowers
2026-08-28


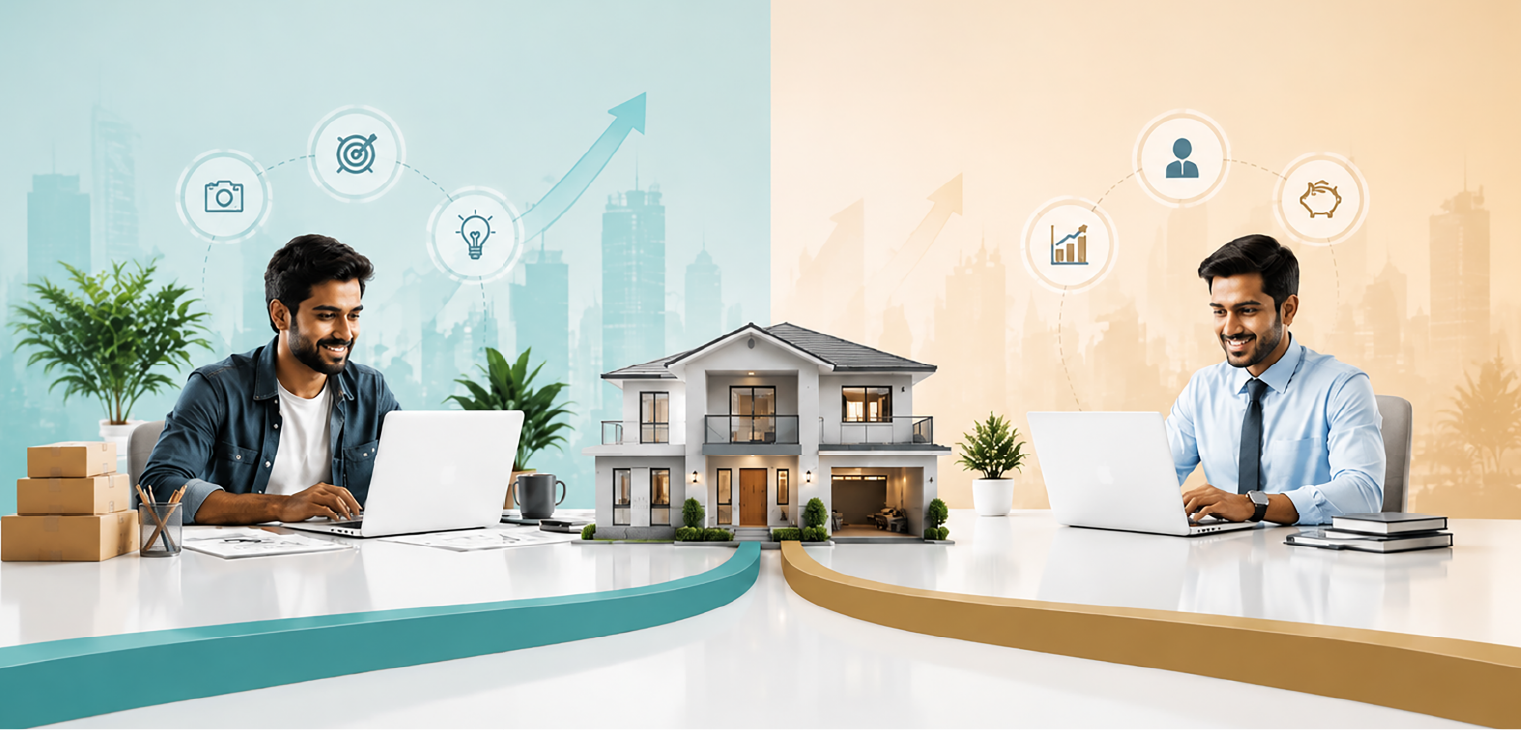
For many people, property is not just an asset — it can also help when funds are needed. A mortgage loan allows borrowers to use their property to access money for different financial needs, such as buying another property, supporting a business, or managing large expenses.
When applying for mortgage loans, lenders usually look at factors like income, repayment capacity, and financial history. Because of this, the way a loan application is evaluated may differ for salaried professionals and self-employed individuals.
While both borrower types can apply for mortgage loans, the documents required and the way income is assessed may vary slightly. Financial institutions such as HDB Financial Services offer mortgage loan solutions designed to support different borrower profiles.
Knowing these differences in advance can help borrowers prepare their applications more confidently and make the process smoother.
Understanding Mortgage Loans
A mortgage loan is a secured loan where the borrower pledges a property as collateral to obtain funds from a lender. The borrower repays the loan over a fixed tenure along with applicable interest.
Mortgage loans are commonly used for purposes such as:
- Purchasing residential or commercial property
- Expanding a business
- Funding large financial needs
- Managing long-term financial goals
Since the loan is secured against property, lenders carefully assess the borrower’s financial profile before approving a mortgage loan.
Mortgage Loans for Salaried Borrowers
Salaried individuals usually receive a fixed monthly income from their employer. This steady income makes it easier for lenders to understand their repayment capacity when they apply for a mortgage loan.
Income Stability
A regular salary helps lenders see that the borrower has a consistent source of income. This makes it easier to assess whether the borrower will be able to repay the loan on time.
Documentation Requirements
To apply for a mortgage loan, salaried borrowers are generally asked to provide documents such as:
- Salary slips for the last few months
- Bank statements
- Employment details or verification
- Identity and address proof
These documents help lenders review the applicant’s financial position and check their mortgage loan eligibility.
Loan Approval Process
Since income records are usually straightforward, the mortgage loan approval process for salaried borrowers may sometimes be quicker.
Mortgage Loans for Self-Employed Borrowers
Self-employed individuals such as entrepreneurs, freelancers, and professionals can also apply for mortgage loans. However, their income may fluctuate depending on business performance.
Because of this, lenders often review their financial records more carefully.
Income Assessment
Instead of salary slips, lenders evaluate the income of self-employed borrowers through business financial records such as profit statements and tax filings.
Business Stability
Lenders often consider how long the business has been operating. A well-established business may strengthen a borrower’s mortgage loan eligibility.
Financial Documentation
Self-employed applicants may need to provide documents such as:
- Income tax returns
- Business financial statements
- Bank statements
- Business registration documents
These records help lenders evaluate repayment capacity before approving a mortgage loan.
Key Differences Between Self-Employed and Salaried Borrowers
Although both groups can apply for mortgage loans, lenders may assess their applications differently.
Despite these differences, both salaried and self-employed borrowers can qualify for mortgage loans if they meet the required criteria.
Factors That Affect Mortgage Loan Eligibility
Several factors can influence mortgage loan eligibility, whether the borrower is salaried or self-employed.
Credit Profile
A good credit history shows that the borrower has managed past financial commitments responsibly. This can improve the chances of getting a mortgage loan approved.
Income Level
Lenders review the borrower’s income to ensure they can comfortably manage regular mortgage loan repayments. Stable and sufficient income generally strengthens loan eligibility.
Property Value
Since the loan is secured against property, the value and legal status of the property are important considerations.
Existing Financial Obligations
Lenders also review existing debts to ensure the borrower can comfortably manage additional loan repayments.
Financial institutions such as HDB Financial Services assess these factors carefully when evaluating a mortgage loan application.
Tips to Improve Mortgage Loan Approval Chances
There are a few simple steps borrowers can take to improve their chances of getting a mortgage loan approved.
Maintain a Good Credit Score
Paying credit card bills and existing loan instalments on time helps build a strong credit history, which lenders often consider during the mortgage loan approval process.
Keep Financial Documents Ready
Keeping income proofs, bank statements, and other financial documents organised can make the mortgage loan application process easier and faster.
Manage Existing Debts
Reducing current financial obligations before applying for a mortgage loan can help improve overall eligibility.
Apply for a Suitable Loan Amount
Choosing a loan amount that matches your income and repayment capacity can increase the chances of loan approval.
Choosing the Right Mortgage Loan Provider
Selecting the right mortgage loan provider is an important part of the borrowing process.
Borrowers often look for lenders that offer:
- Transparent loan terms
- Competitive mortgage loan interest rates
- Efficient loan processing
- Flexible repayment options
Financial institutions such as HDB Financial Services offer mortgage loan solutions designed to meet the needs of both salaried and self-employed borrowers.
Conclusion
A mortgage loan can be a useful financial option for both salaried and self-employed individuals who want to access funds against property. While the application process may differ slightly for each borrower type, both can qualify for mortgage loans by meeting the required eligibility criteria and providing the necessary documents.
Salaried borrowers often benefit from stable income records, while self-employed individuals may need to show consistent business income through financial documents. Understanding these differences can help borrowers prepare better before applying.
Choosing the right mortgage loan provider and maintaining a strong financial profile can also make the process smoother and improve the chances of loan approval.
| Factor | Salaried Borrowers | Self-Employed Borrowers |
|---|---|---|
| Income Type | Fixed monthly salary | Variable business income |
| Income Verification | Salary slips and employer records | Business financial statements |
| Documentation | Usually simpler | Often more detailed |
| Income Stability | Generally predictable | May fluctuate |